Deal & Transaction Services

The broker's numbers are a recast. The bank's numbers are the only ones that matter.

Independent financial analysis for people buying and selling small businesses. We reconcile the story to filed tax returns and bank statements — before you sign, and before a lender does it for you.

✓ 25+ years in corporate accounting and finance ✓ Deals from $150K to $5M ✓ Flat fee, scoped before you pay ✓ Charlotte, NC — engagements nationwide
Two sides of the table

Which side of the deal are you on?

The work looks similar from the outside. Who it's for, and what it's protecting you from, is completely different.

If you're selling

Pre-Sale Financial Analysis

Most owners find out their numbers won't hold up six months into a deal, from a buyer's lender, when it's far too late to fix anything. Find out now, while you still can.

  • Normalize earnings the way a buyer's analyst will
  • Document and substantiate every add-back, so they survive scrutiny
  • Reconcile the books to your filed returns and bank statements
  • Run the business through a lender's debt service coverage test
  • Fix what's fixable before the listing goes live
If you're buying

Quality of Earnings

You're about to sign a personal guarantee on somebody else's bookkeeping. The lender will test these numbers whether you do or not — better that you see them first.

  • Independent analysis, working only for you
  • Every add-back tested against the general ledger
  • Cash proof — reported receipts tied to actual bank statements
  • Revenue quality and customer concentration
  • The deal run through the lender's actual coverage formula
What turns up

The things that kill small deals.

None of these are exotic. They're what's actually sitting in the books of businesses this size, every time.

Revenue that moved, expenses that didn't

Reviewed statements come back lighter on revenue than the broker's package, with expenses identical. Only the income line moved — and somebody on the other side knew.

Add-backs that won't survive the lender

Owner comp, personal vehicles, and "one-time" expenses that recur every single year. Your SDE recast is only worth what the bank's add-back policy actually allows.

Coverage that doesn't clear

We run the deal through the lender's real formula — 1.25x on an acquisition — before you're emotionally committed, not after the bank says no and the price has to move.

Customers who leave with the seller

Concentration is only half of it. The question is which contracts survive a change of ownership and which were really relationships with the person selling.

Cash that doesn't tie out

Reported receipts and disbursements reconciled against actual bank statements for the trailing twelve months and the two prior fiscal years. Books can be edited. Bank statements can't.

A balance sheet stacked against you

SBA note plus a line of credit plus a seller note plus a seller lease, with a deed of trust on your house — and the seller as lender, landlord and consultant at once. We model the conservative case.

Timing

When to call — and when not to spend the money.

Before the LOI

A deal screen is cheap. A bad deal isn't.

Before you commit time and legal fees, a short engagement ties the seller's P&L to filed returns, scrubs the add-backs, and tests coverage. If the deal doesn't survive that, you've learned it for a fraction of what the next stage costs.

Don't do this

Never pay for diligence before the documents arrive.

A signed LOI is not the same as a seller who will produce records. If the diligence package is thirty days late and the request list is unanswered, that is your answer — and it's a free one. Hold your money until the documents are in hand.

Engagements

Scoped before you pay. Flat fee, never hourly.

A short call establishes what the deal needs. You get a written scope and a fixed fee before any work begins — no retainers, no hourly surprises.

Deal Screen
$150K – $750K
$1,500 – $5,000
What it covers
  • Tax return to P&L tie-out
  • Add-back scrub against the books
  • Debt service coverage test
  • Written red-flag summary
  • Debrief call
What we need
  • Federal tax returns, 3 most recent years, all schedules
  • Profit & loss statements, 3 fiscal years + TTM
  • Seller's add-back or recast schedule, with support
  • Asking price and proposed deal terms
5 business days from complete records
Focused QoE
$750K – $3M
$5,000 – $15,000
What it covers
  • Everything in the Deal Screen
  • Cash proof against bank statements
  • Revenue quality & customer concentration
  • Working capital analysis
  • Lender-ready written report
What we need
  • Everything in the Deal Screen list
  • Bank statements, all accounts, 3 years + TTM
  • General ledger detail, same periods
  • Balance sheets, 3 year-ends + monthly for the TTM
  • Payroll registers and W-2/W-3 summaries
  • Revenue by customer and monthly revenue detail
  • Debt schedule and loan agreements
2 weeks from complete records
Full QoE
$3M – $5M
$15,000 – $25,000
What it covers
  • Full scope, 3 years plus year to date
  • Cash proof for TTM and two fiscal years
  • Normalized earnings schedule with support
  • Structured data book alongside the report
  • Formatted for SBA change-of-ownership review
What we need
  • Everything in the Focused QoE list
  • A/R and A/P aging, each year-end and TTM end
  • Accrued liabilities detail (PTO, bonuses, taxes)
  • Year-to-date interim statements
  • Customer and supplier contracts
  • Equipment list and lease agreements
  • IRS tax transcripts (Form 8821 signed by seller)
  • CIM or listing package, if one exists
2–4 weeks from complete records
If you're selling
Pre-Sale Financial Analysis
Sellers under $3M
$1,500 – $5,000
2 weeks from complete records
What it covers
  • Recast SDE with support behind every add-back
  • Proof of cash against bank statements
  • Tested against a lender's coverage requirement
  • Data-room checklist and an issues list to fix before listing
What we need
  • Federal tax returns, 3 most recent years
  • P&Ls, balance sheets and year-to-date interim statements
  • Bank statements and general ledger detail
  • Payroll registers, revenue by customer, monthly revenue
  • A/R and A/P aging, debt schedule, equipment list
  • Your target price

A Pre-Sale Financial Analysis prepares you for a buyer’s diligence — it does not replace it, and it does not satisfy the SBA’s lender-engaged requirement at $3M and above. Tell us about the business →

Terms: 50% at engagement, balance at delivery. Fees are never contingent on the deal closing or on loan approval — a contingent fee would undercut the independence the report depends on.

Buying or selling a trucking company? Fuel and IFTA reconciliation, factoring reserves, equipment replacement, 1099 owner-operator exposure and operating-authority transfer all change the earnings picture — and we also run a bookkeeping practice for owner-operators. See what we check on a trucking deal →

Scope

What's in, what's out, and the rules we work by.

What the engagement covers

  • Normalized earnings and a documented adjustment schedule
  • Add-back substantiation tied back to source records
  • Reconciliation of statements to filed tax returns and the general ledger
  • Cash proof against business bank statements
  • Revenue quality, customer concentration and contract durability
  • Working capital and debt service coverage analysis

What it does not cover

  • Legal diligence — use an attorney
  • Tax structuring and opinions
  • Business valuation or a fairness opinion
  • Operational, IT, or environmental diligence
  • Audits, reviews, compilations, or any attest service

How we work

  • We never work both sides of the same deal. Buy-side and sell-side are different jobs for different people, and doing both would make neither one worth anything.
  • A sell-side analysis prepares you for diligence — it doesn't replace the buyer's. Any buyer will discount work the seller paid for, and a sell-side report does not satisfy the SBA's lender-engaged requirement.
  • Add-backs get documented, not maximized. A seller talked out of three aggressive add-backs before listing is in a far better position than one caught with them in diligence.
  • If the records don't support a number, it doesn't go in the report. That includes numbers you were hoping for.
Lenders & brokers

Engaged directly by the lender.

Under SOP 50 10 8.1, effective October 1, 2026, SBA 7(a) change-of-ownership loans at a purchase price of $3 million or more require an independent quality of earnings report engaged by the lender — not by the borrower or the seller. Below that threshold a report is discretionary, and many lenders still want one before they underwrite.

We work to your add-back policy and your coverage threshold, and we'll say plainly when a deal doesn't clear it.

Brokers: a listing whose books won't survive diligence is a year of your time. A seller who gets the financial work done before going to market closes faster and retrades less.

Who does the work

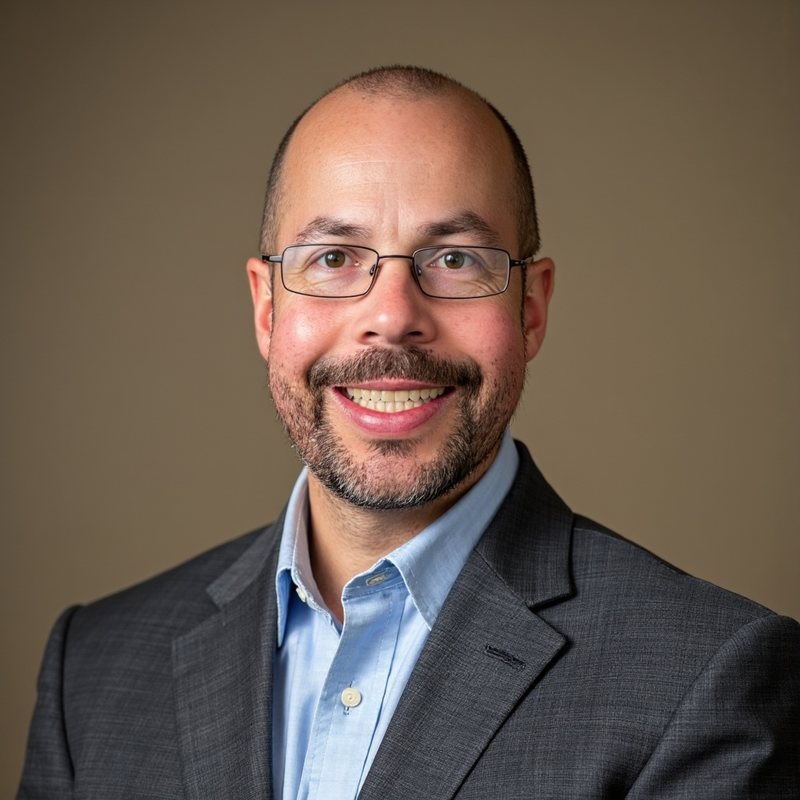
Every engagement is done by me.

Bert Gonzalez, Founder of Four Bookkeeping and Accounting

Bert Gonzalez

Founder & Lead Accountant

Every engagement is done by me. Not a staff analyst, not an offshore team working from a template.

I spent twenty-five years in corporate accounting and finance before this — Big Four public accounting, Corporate Controller, VP of Finance at a manufacturer doing over $250 million in revenue, and Chief Financial Officer. Along the way I helped run a CPA practice serving small-business clients.

Which means I haven't only read these deals from the outside. I have closed the books, built the add-back schedule, sat across the table from the lender, and been the person a buyer's diligence team was asking questions of. I know where the numbers get soft, because I've been on the side that had to explain them.

I'm also evaluating acquisitions myself. I read these packages as a buyer, not just as an accountant.

25+ Years Big Four Controller VP of Finance CFO Charlotte, NC Nationwide
Questions

What buyers and sellers ask first.

What is a quality of earnings report?
It tests whether a business's reported profit is real and repeatable. We reconcile the seller's statements to filed tax returns, general ledger detail and bank statements, substantiate or reject each add-back, examine revenue quality and customer concentration, and arrive at a normalized earnings figure you and your lender can actually rely on. It is a non-attest advisory engagement, not an audit.
Do I need a quality of earnings report for an SBA loan?
Under SBA SOP 50 10 8.1, effective October 1, 2026, 7(a) change-of-ownership loans with a purchase price of $3 million or more require an independent quality of earnings report engaged by the lender. A report commissioned by the buyer or the seller does not satisfy that requirement. Below $3 million nothing is mandated — but the lender will still test the numbers in underwriting, and many buyers commission their own analysis regardless.
How is this different from an audit?
An audit expresses an opinion on whether financial statements conform to accounting standards, and only a licensed CPA firm can perform one. A quality of earnings analysis is a non-attest advisory engagement answering a single question: what are the real, ongoing earnings of this business? It looks at what you're actually buying rather than at statement conformity — and it's faster and far less expensive.
I'm selling. When should I start?
Several months before you list — earlier than almost any owner does. A pre-sale analysis normalizes your earnings, documents your add-backs so they hold up under scrutiny, reconciles the books to your filed returns, and tests the business against a lender's coverage requirement. At that stage, problems are fixable. Discovered during a buyer's diligence, the same problems cost you price or cost you the deal.
Can a buyer rely on the report I paid for as the seller?
Not as a replacement for their own diligence, and we won't tell you otherwise. A sell-side analysis is preparation: it speeds things up and removes surprises. But any serious buyer discounts work the other side paid for, and a sell-side report does not satisfy the SBA's lender-engaged requirement. We also never work both sides of the same deal.
What size deals do you work on?
Purchase prices from roughly $150,000 to $5 million. This is deliberately the range the national and regional firms decline, because their engagement minimums sit above it — and it's where most SBA-financed Main Street deals actually happen.
What documents do you need to get started?
It depends on the engagement — each card above lists exactly what it needs. A Deal Screen starts with three years of filed returns, P&Ls plus TTM, and your add-back schedule. A Focused QoE adds bank statements, general ledger detail, balance sheets, payroll and revenue by customer; a Full QoE adds A/R and A/P aging, accrued liabilities, interim statements, contracts, IRS transcripts and the CIM. If a seller won't produce bank statements or general ledger detail, that refusal is itself a finding — and worth knowing early.
How long does it take?
A Deal Screen runs about five business days from receipt of complete records, a Focused QoE about two weeks, and a Full QoE two to four weeks. In practice the longest part is usually the seller producing documents, which is why we quote from the date records are complete rather than from the engagement date.
Let's talk

Tell us about the deal.

A short call, no obligation. We'll tell you what the engagement would cover, what it would cost, and whether you need one at all.

We'll never share your info. Or call / text (704) 981-1211.

About these services. Quality of earnings analysis and pre-sale financial analysis are non-attest advisory engagements. They are not audits, reviews, compilations, or any other attest service as defined by the AICPA, and no opinion or assurance is expressed on any financial statement. Four Bookkeeping and Accounting, LLC is not a CPA firm. Findings are based on records provided by the seller or the business owner, and a report's usefulness depends on the completeness and accuracy of those records. Nothing on this page is legal, tax, or investment advice.